Cash flow is one of the most important concepts in rental real estate, but it is often misunderstood.
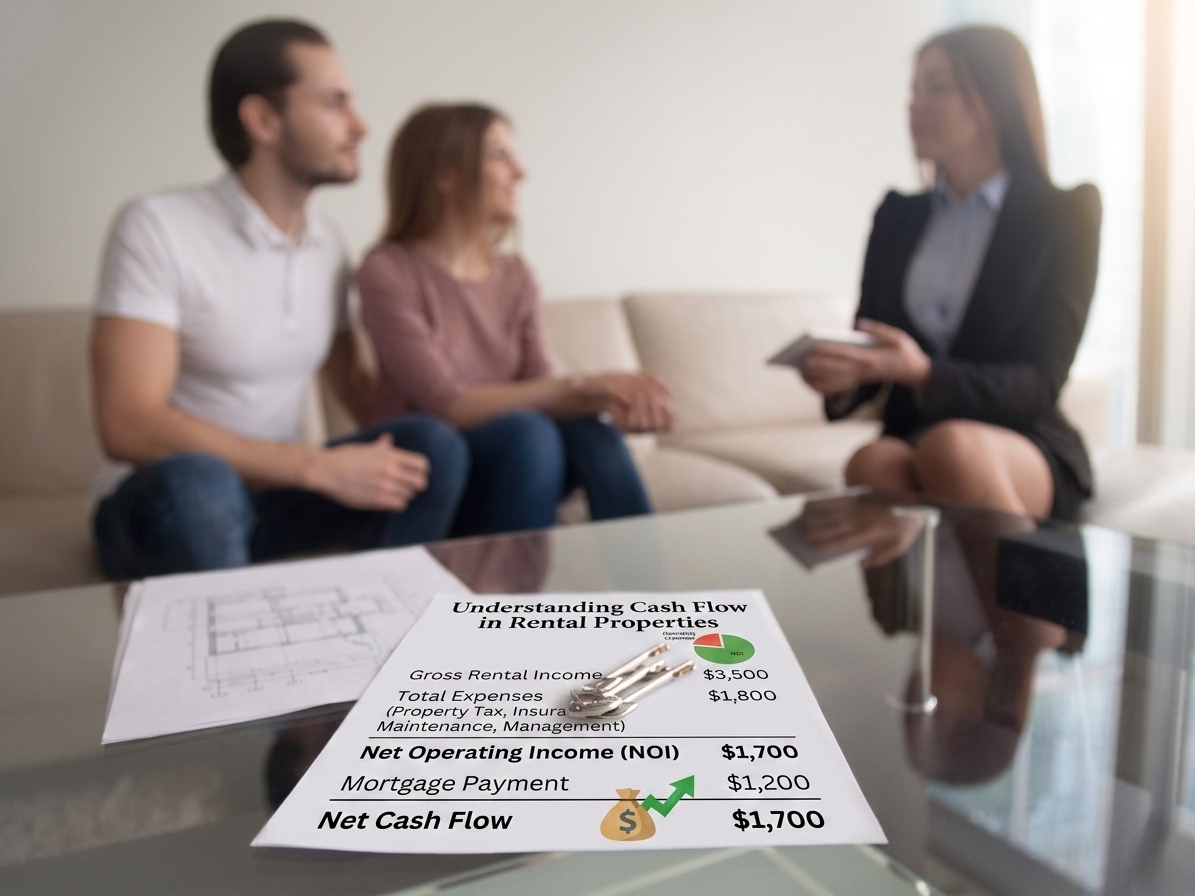
Basic rental cash flow is the money left after rental income and expenses, including debt service. The challenge is determining which expenses belong in the model.
Start with rent. Use realistic market rent and account for vacancy or collection losses.
Then subtract operating expenses. Property taxes, insurance, repairs, maintenance, management, utilities, landscaping, common charges, and other recurring expenses can materially reduce income.
Capital expenditures deserve special attention. Roofs, HVAC systems, appliances, parking surfaces, and other major components eventually require replacement. Investors should reserve money for these expenses even if no large repair is currently needed.
After operating expenses, account for financing costs. The remaining amount is the property’s projected cash flow before taxes.
A property can have positive monthly cash flow and still provide a poor overall return if the investor paid too much or used excessive capital.
Conversely, a property with modest initial cash flow may have other strengths, such as strong appreciation potential, principal reduction, or strategic location.
The correct analysis therefore looks at multiple measures: cash flow, cap rate, cash-on-cash return, debt service, equity growth, and total return.
Investors should also run stress tests. Model lower rent, higher vacancy, increased insurance, higher maintenance, or unexpected capital expenses.
Real estate investing rewards conservative underwriting. A deal that works only when everything goes perfectly is not necessarily a good deal.
Thinking about buying, selling, or investing in New Jersey or New York? Contact Citi Living Solutions to discuss your goals and next steps.